Zenith, or the Louis Vuitton recipe put to the test of a manufacture
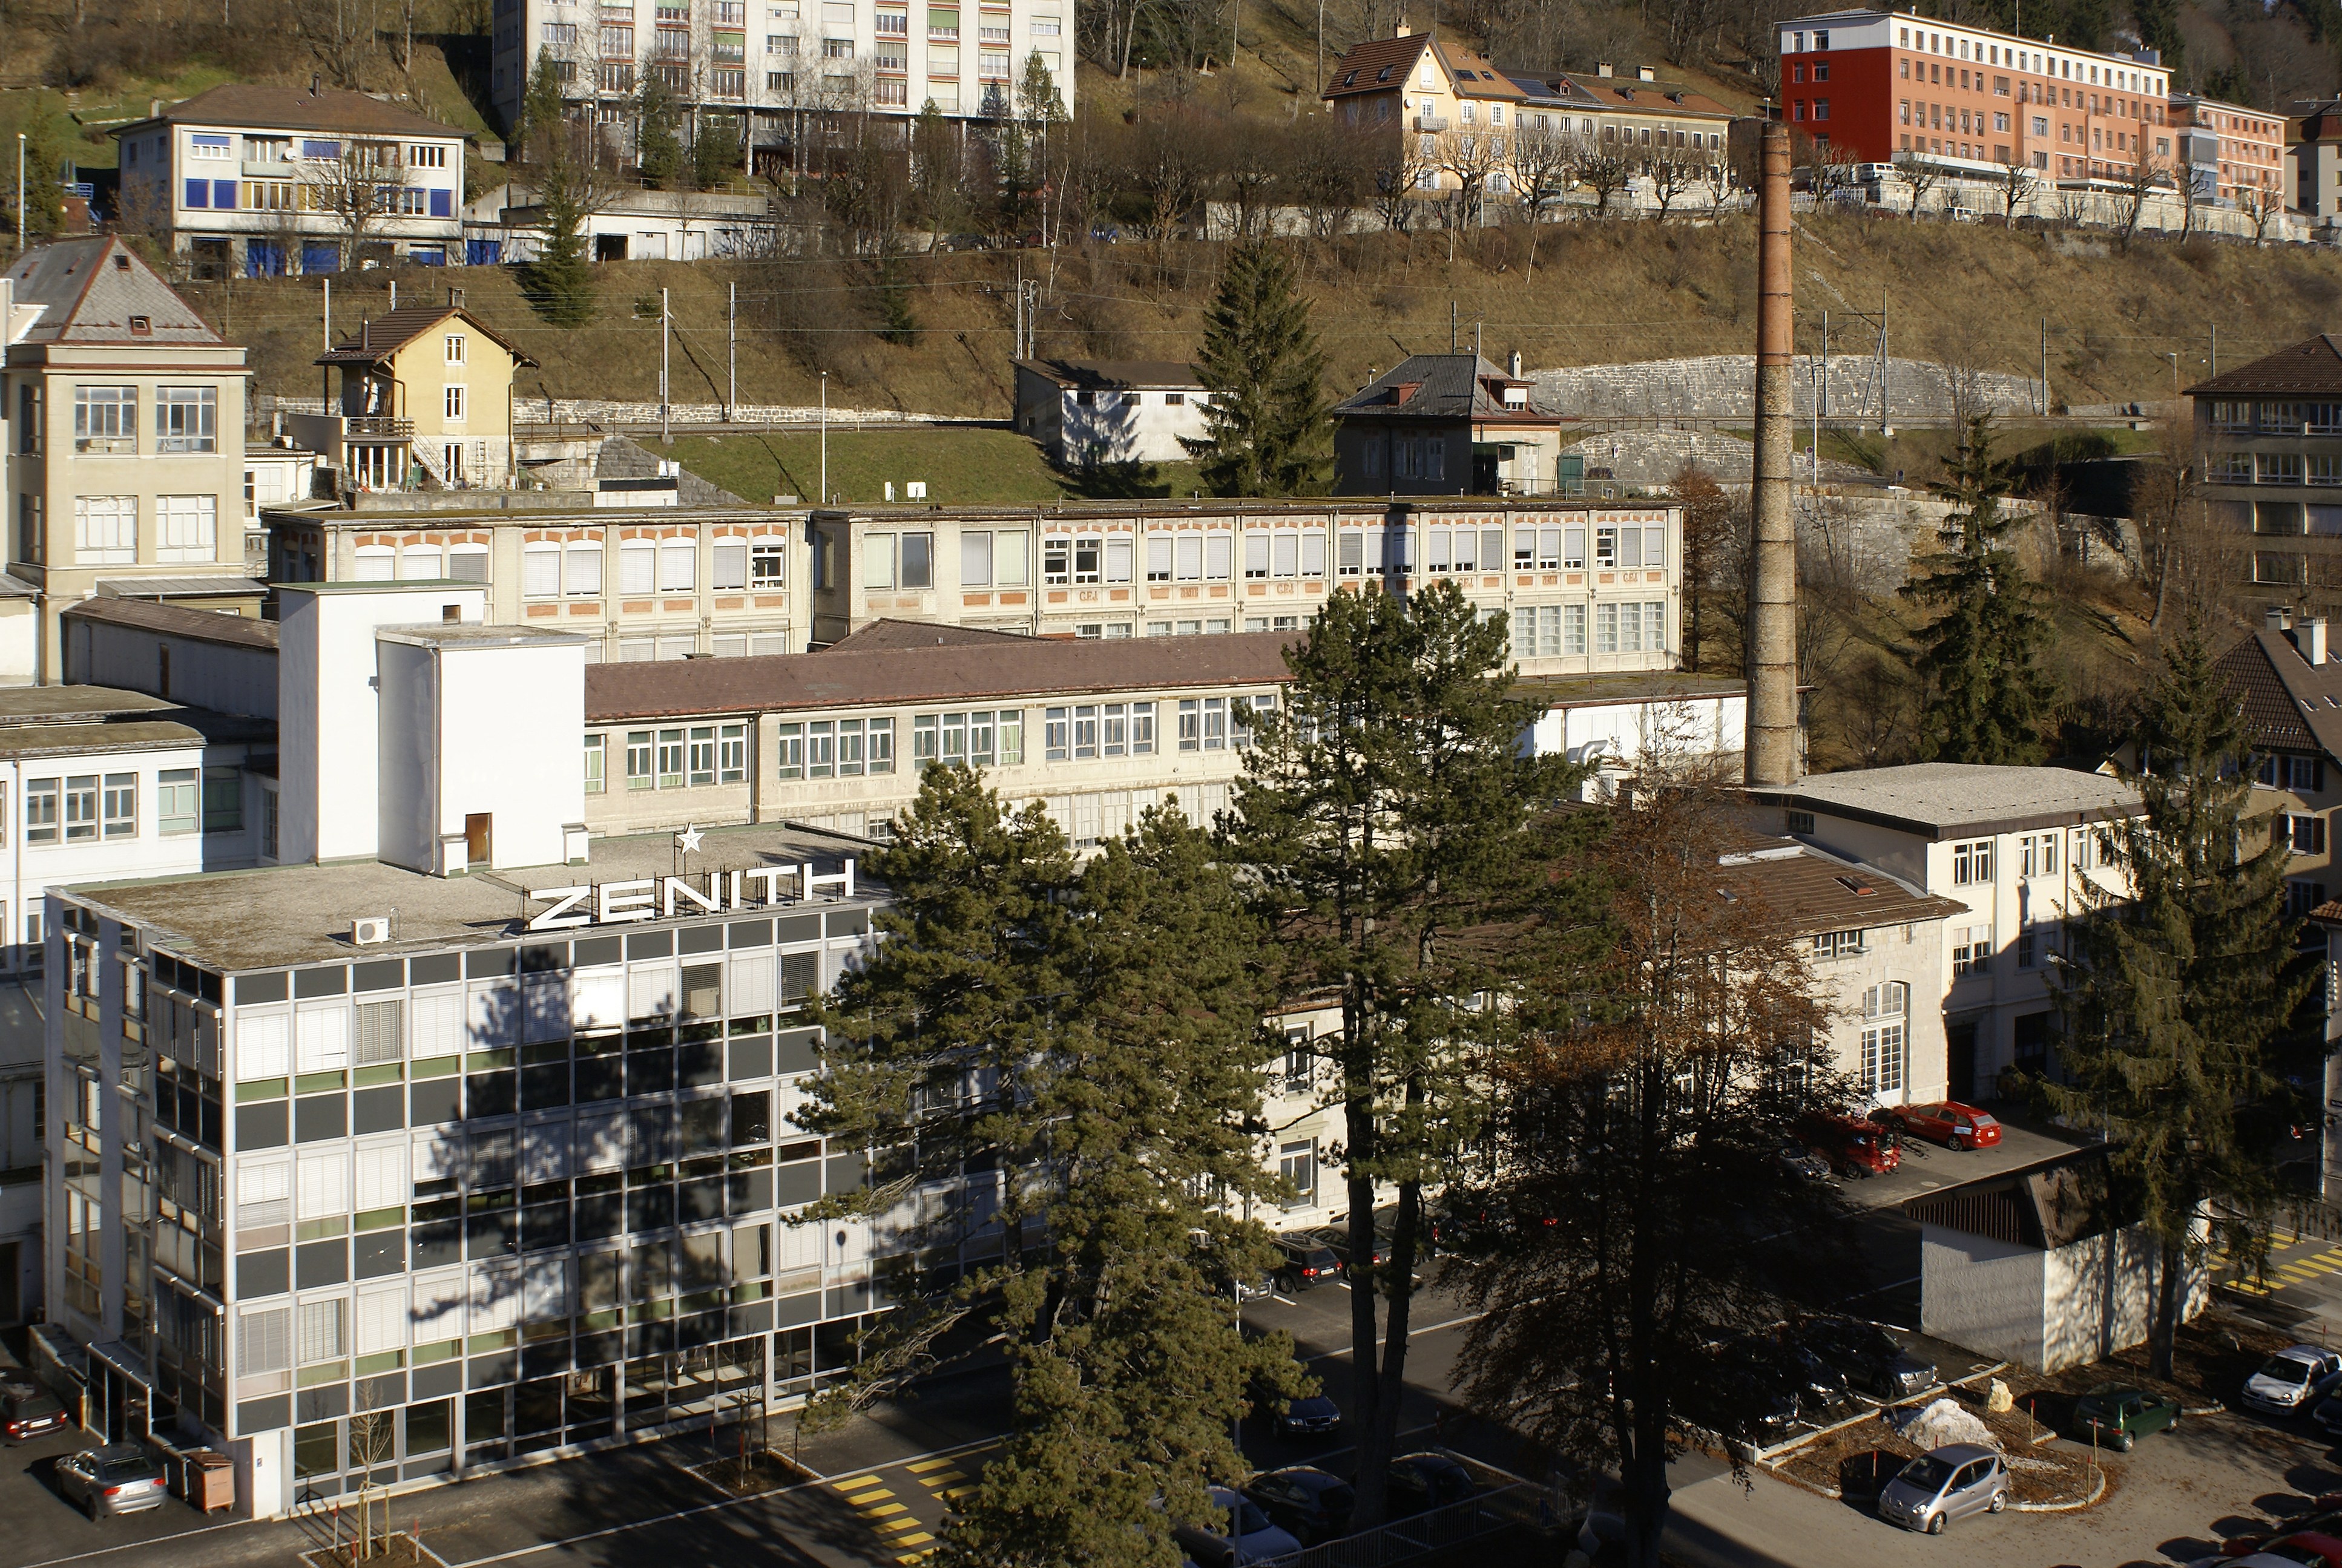
On 14 November 2024 Frédéric Arnault, then head of LVMH’s watch division, announced that Zenith was going to become more than a brand. The group wanted to turn it into a movement maker for all of its houses. On the morning of 22 October 2026, in Le Locle, Benoît de Clerck, Zenith’s chief executive, told his staff that around a hundred jobs, half the manufacture, could go. Yet the plan spares one activity: making calibres for the group’s other brands. What is being cut is the brand. The 2024 promise still stands, just not in the way anyone imagined.
What was announced in Le Locle
Zenith confirmed it had opened “a staff consultation as part of a strategic repositioning project for the Maison”. The process runs until 12 November. According to Le Temps, which broke the story, around a hundred of the manufacture’s 200 or so jobs are affected, along with around a hundred more outside Switzerland, where the distribution and boutique network is to be reduced. Most of the current collection would be discontinued in the short term. After-sales service is untouched, and management says that “internal mobility will be a priority” within LVMH.
Le Temps obtained a transcript of part of the address given by Benoît de Clerck, in post since January 2024. He first describes a climate hitting the whole mid-range segment, “including right here in Le Locle, a few days ago, with Montblanc”: the strong franc, American tariffs, the decline of the Middle East and Asia, “a market that has changed for good”. Then he turns to Zenith itself, with a candour rarely heard in a restructuring speech.
Among these difficulties: a position in a highly competitive segment, up against Maisons with considerable marketing power compared with ours, and an industrial and commercial structure sized for far more than we sell, which weighs heavily on our costs.
Benoît de Clerck, chief executive of Zenith, addressing staff, 22 October 2026, quoted by Le Temps, translated from the French
The brand has been accumulating losses for several years, the amount of which has not been made public. “No company can lose money indefinitely,” he concluded, setting a course: 2029.
That course can be read in the shift in price positioning. The heart of the current range sits between 8,000 and 15,000 Swiss francs. The brand would leave it to turn towards haute horlogerie, building on the G.F.J. Calibre 135, presented at Watches and Wonders in 2025, a prizewinner in the chronometry category at the latest Grand Prix d’Horlogerie de Genève, and starting at just under 50,000 Swiss francs.
Zenith does not publish its accounts. In February Morgan Stanley and LuxeConsult estimated its 2025 revenue at 98 million Swiss francs, for around 8,500 watches, down 15% year on year. These are analysts’ reconstructions, not audited figures, but the order of magnitude is right: the 38th Swiss brand, and the smallest of the group’s three pure watch houses, alongside TAG Heuer and Hublot.
A recipe already served in the group
The plan has a precedent under the same roof. Since 2023 Louis Vuitton has tightened its watch range and relaunched the Tambour much higher up. According to Morgan Stanley, its volumes were halved in 2025, to around 12,000 watches, while the average price doubled, to 13,750 francs. The same report drew a general rule from it that now reads like a summary of the Zenith plan.
Premium repositioning often requires deliberate volume contraction.
Morgan Stanley and LuxeConsult, Swiss Watcher, February 2026
The whole difference lies in the proportions. At Louis Vuitton, watches account for less than 1% of the brand’s sales, again according to Morgan Stanley, and behind the Tambour stand around 450 directly operated stores. At Zenith, watches are the brand’s entire business. The group had never before applied the recipe to a house that is a watchmaker by history.
The comparison also cuts the other way. To win over collectors, Louis Vuitton teamed up with independents: Rexhep Rexhepi, Kari Voutilainen, De Bethune. Zenith has no such problem: the El Primero, launched in 1969, gives it its technical legitimacy. What it still lacks, Benoît de Clerck told his teams himself: marketing clout, in other words desire, and the network able to turn it into sales at 50,000 francs.
One manufacture, two trades
One detail changes how the plan reads. The Le Locle manufacture also produces mechanical calibres for other brands in the group, and this activity “will remain in place”. Its order book is full “until 2027”, according to Benoît de Clerck. Zenith already supplies Hublot and has supplied TAG Heuer in the past.
Le Locle will therefore house two businesses under one name. One is an industrial supplier, paid by volume, whose health depends on orders from its sister houses. The other is a small haute horlogerie house, paid by scarcity, which has to make people want watches at 50,000 francs. Frédéric Arnault wanted an engine maker backed by a brand. The 2026 plan keeps the engine maker and cuts the brand down to what it can sell. Which of the two will carry the other remains to be seen.
At the price of a Rolex
Morgan Stanley’s estimates shed light on Benoît de Clerck’s remark about his competitors’ marketing power. The average selling price of a Zenith, excluding tax, would be around 15,600 francs. That of a Rolex, around 14,000. On the floor where it sold most of its watches, Zenith was up against the world’s leading brand, which sells around 1.15 million a year, more than a hundred and thirty times as many, as well as Jaeger-LeCoultre and Panerai at Richemont.
By leaving this price bracket, Zenith leaves LVMH without a pure watch brand between TAG Heuer and the very top end. TAG Heuer sells around 342,000 watches, at 2,710 francs on average. Above it come the houses’ own watches, Bulgari, Louis Vuitton and Dior, between 10,000 and 18,000 francs on average, bought first and foremost by those houses’ clients. Then Hublot, at around 20,000 francs. And finally, tomorrow, haute horlogerie: Zenith, Daniel Roth, Gérald Genta and Louis Vuitton’s grand pieces, the last three relaunched or developed since 2023 by La Fabrique du Temps, under the leadership of Jean Arnault.
Swatch Group built its portfolio like a staircase, one brand per step: Tissot at around 470 francs, Longines around 1,900, Omega around 6,800, Breguet around 35,000. The one LVMH is drawing looks more like an hourglass. Plenty of volume at the bottom with TAG Heuer, several signatures at the top, and almost nothing left in the middle. Above 20,000 francs, five brands from the same group will be speaking to the same collector, and price will no longer be enough to tell them apart.
On paper, it is no small challenge to hold a sound strategy built on a clear catalogue without sowing confusion and fog.
Prices change, and so do the bosses
Frédéric Arnault ran the watch division from January 2024 to March 2025. Jean-Christophe Babin succeeded him on 1 April 2025. On 29 April 2026 he acknowledged to Bloomberg that, for mid-market brands such as Zenith, “the game is tougher”. In the same interview he named Jean Arnault as “the perfect person to take over that division”. Several press titles have presented him since the spring as the new head of the group’s watch houses; to our knowledge, LVMH has not announced it officially, but the Zenith plan is clearly his initiative.
Hublot is on the same path. On 15 October, according to press reports on which the brand did not comment, François-Henri Bennahmias, who ran Audemars Piguet from 2012 to the end of 2023, joined the brand as a consultant. Morgan Stanley’s estimates offer a few clues as to why one would go looking for this particular man: in 2025 Audemars Piguet is thought to have sold fewer than twice as many watches as Hublot, around 53,000 against 32,000, for revenue almost six times higher, 2.6 billion francs against 460 million. He knows how, undeniably, but can a Classic Fusion already be compared with a Royal Oak today?
The stakes go beyond the two brands. LVMH’s share of Swiss watchmaking is estimated at 5.3% in 2025: the sixth-largest group, behind Patek Philippe which, on its own, would account for 7%.
What is at stake before January
On 12 November the end of the consultation will show how many jobs are actually cut; Le Temps notes that some might be spared. Then comes the succession to Jean-Christophe Babin: an official appointment of Jean Arnault would give the Zenith plan a clear signature. Then LVMH Watch Week, in January, the first chance to see what remains of the current collection. Further out, 2027 will mark the end of the supplier’s order book: if the sister houses slow down then, both of Le Locle’s trades will suffer at the same time.
That leaves the overall design. What follows is a hypothesis, a simplistic one no doubt, built from what each brand already does. If price no longer separates the houses at the top, each will have to hold a territory. Hublot has that of materials, daring and now art, with Jeff Koons, who became its ambassador in September. Zenith can lay claim to chronometry and high frequency, that of the El Primero and of the Calibre 135, awarded in precisely that category. Daniel Roth holds discreet classicism and guilloché, Gérald Genta design and colour, with the Oursin. Louis Vuitton keeps its clients, travel, and the exceptional pieces signed with independents.
In theory, the division holds up. It still leaves two contradictions. If Hublot moves up towards Audemars Piguet, as the choice of François-Henri Bennahmias may suggest, the brand will cross paths with the new Zenith at around 50,000 francs. Gérald Genta and Louis Vuitton, for their part, are addressing the same well-off, fashion-minded female client. And the middle stays empty: between 5,000 and 15,000 francs, nothing in the group is aimed any longer at the enthusiast who wants fine mechanics without going through a fashion or jewellery house. Could TAG Heuer’s most expensive models be called on to fill that gap?
What it reveals
In watchmaking, LVMH seems to be taking the opposite tack to the logic that made its fortune elsewhere. The group grew through scale, network and the power of its names. Faced with watches, it is going the other way: fewer pieces, more expensive ones, and an adviser from Audemars Piguet. The model it is aiming for logically looks more like that of the great family-owned watch houses than that of a conglomerate.
That is where the blind spot lies. The scarcity of Patek Philippe and Audemars Piguet was built on decades of continuity: the same families, the same lines, leaders who stay. François-Henri Bennahmias ran Audemars Piguet for more than ten years. LVMH’s watchmaking has changed boss twice in two years. A brand can decide to produce less. It cannot decide that people will wait for its watches. What the group will most likely lack to make the recipe work is time.
One last question goes beyond LVMH. In August we asked whether the Swiss watch had given up on beginners. Benoît de Clerck cites Montblanc, in Le Locle, a few days before him. If the world’s leading luxury group in turn leaves the 8,000 to 15,000 franc floor, the question moves up a step: apart from the most powerful, who will still be able to make a living there?
Sources: Le Temps, article of 22 October 2026 revealing Zenith’s repositioning, with a partial transcript of Benoît de Clerck’s address
Zenith, statement to the awp agency of 22 October 2026, carried by ATS and AFP
Bloomberg, interview with Frédéric Arnault of 14 November 2024, carried by swissinfo.ch on 15 November 2024
Bloomberg, interview with Jean-Christophe Babin of 29 April 2026, carried by swissinfo.ch
LVMH, press release on the appointment of Jean-Christophe Babin, 28 March 2025
Hublot, press release of 9 September 2026 on Jeff Koons
Moncler, profile of François-Henri Bennahmias on the board of directors, monclergroup.com
Morgan Stanley and LuxeConsult, Swiss Watcher report, February 2026, brand-by-brand estimates of revenue, volumes and average selling price excluding tax.
Research and writing assisted by Claude Code.